Home financing allows many buyers to purchase residential property without paying the entire cost upfront. Yet choosing Loanable Flats involves more than finding a property and applying for the maximum amount available from a lender.
A successful purchase requires buyers to understand property eligibility, their own borrowing capacity, upfront expenses, monthly repayments, and the documentation involved.
For homebuyers in Jaipur, Rajasthan, preparing these details before booking can make the purchase process more manageable.
Understand What Home Loan Eligibility Means
Two different forms of assessment can influence a financed property purchase.
The first concerns the borrower. Financial institutions typically assess factors such as income, existing liabilities, credit history, age, employment profile, and repayment capacity according to their lending policies.
The second concerns the property.
Lenders may examine project and property documentation before approving finance. Requirements vary between institutions and individual transactions.
This means a buyer's personal loan eligibility does not automatically confirm that every shortlisted property will receive financing.
Estimate the Down Payment Early
Home loans generally do not remove the need for personal funds.
Buyers should calculate how much money they can comfortably contribute without exhausting emergency savings.
The upfront budget may need to cover the buyer's contribution toward the property as well as other transaction-related expenses that may not be fully financed.
Keeping a financial reserve after the purchase can be important for interiors, furniture, moving expenses, and unexpected household costs.
Calculate a Comfortable EMI
Loan eligibility and comfortable affordability are not always the same thing.
A lender may approve an amount that creates a higher monthly repayment than the household would prefer.
Before selecting a property, compare the proposed EMI with regular commitments such as:
- Household expenses
- Education costs
- Existing loan payments
- Insurance
- Savings
- Investments
- Family responsibilities
- Emergency requirements
The objective should be sustainable homeownership rather than simply maximising borrowing capacity.
Keep Financial Documents Organised
Loan applications typically require identity, income, banking, and property-related documents based on the lender's requirements and the applicant's profile.
Preparing documents early can reduce delays.
Salaried applicants and self-employed applicants may have different documentation requirements, so buyers should understand what applies to their circumstances before committing to a purchase timeline.
Review the Property Information
When evaluating a financed purchase, buyers should examine relevant property documentation and understand the project's applicable registration and approval details.
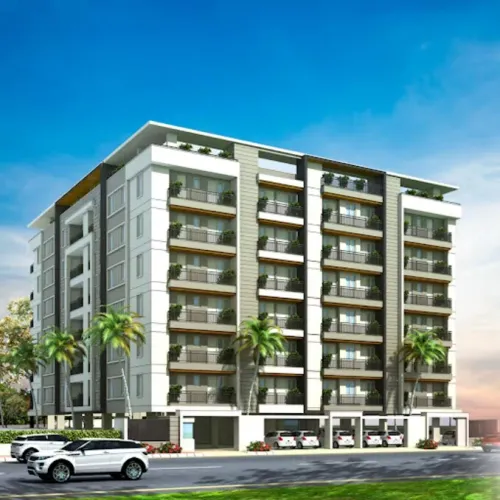
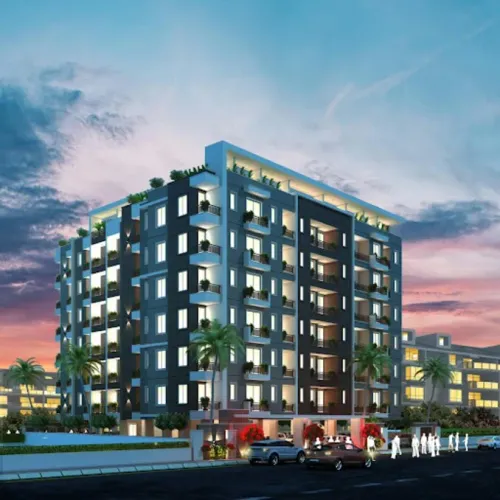
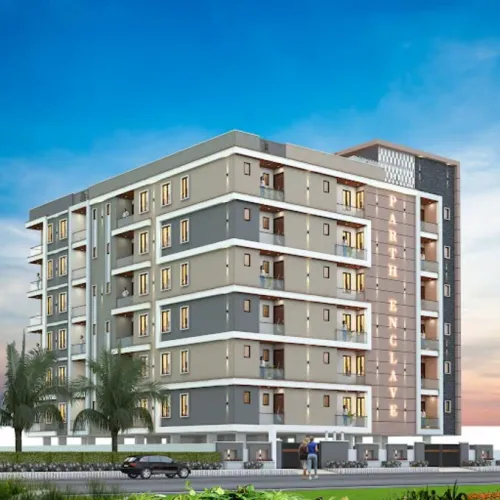
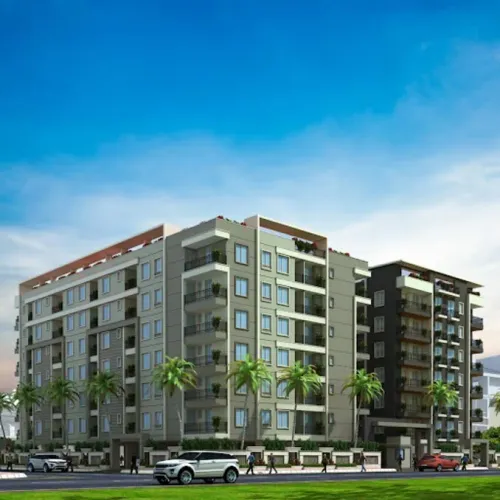
Homebuyers considering Parth Residency can discuss available residential options and then evaluate financing according to the specific property, buyer profile, and lender requirements.
Loan availability should be confirmed through the appropriate financing process rather than assumed from general statements.
Compare the Total Cost of Borrowing
The interest rate is important, but it is not the only consideration.
Buyers should understand the loan tenure, processing charges, repayment structure, applicable conditions, and how changes in interest rates may affect repayment when relevant.
A longer tenure may reduce the monthly EMI while increasing the total interest paid over time.
A shorter tenure may reduce overall interest but create a higher monthly commitment.
The right balance depends on household cash flow.
Coordinate Property Selection with Financial Readiness
Property search and financing should ideally happen together.
Before finalising a home in Jaipur, establish a realistic budget, estimate the down payment, understand likely borrowing capacity, examine the total acquisition cost, and keep documentation ready.
Then compare properties within that financial range.
This approach prevents buyers from becoming attached to a home that creates unnecessary financial strain.
A home loan is most useful when it supports a carefully planned purchase. By understanding both property-related requirements and personal repayment capacity, buyers can approach residential ownership with greater clarity and build a financial structure that remains manageable long after the keys are handed over.
Keywords